The Great Egg Grab: How Surging Egg Prices Are Fueling Global Egg M&A
Eggs — once the dullest corner of the grocery aisle — have suddenly become one of the hottest commodities in global agrifood. Prices have soared, margins have widened, and a wave of industrial-scale consolidation is sweeping across the sector at breakneck speed. From Brazil to Spain to the U.S. Midwest, the world’s largest producers are racing to buy capacity, secure feed, and lock in resilience as eggs transform from a basic staple into a billion-dollar strategic asset.
Average price per dozen eggs in the U.S. (1980-2025)
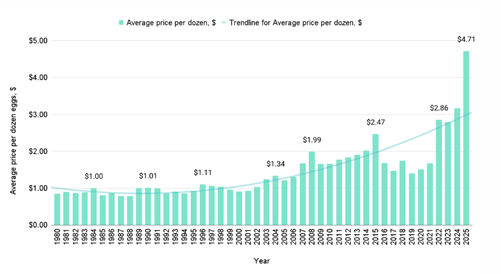
Source: FRED
Resilient Demand
Demand for eggs has stayed remarkably firm. As one of the lowest-cost sources of premium protein, even sharp price swings have limited impact on household spending. Functional substitutes simply don’t exist for baking, food processing or breakfast consumption, keeping volumes stable. Retailers further entrench this resilience by treating eggs as a traffic-driving essential, preserving shelf space regardless of pricing. In emerging economies, rising incomes and steady growth in per-capita consumption reinforce this structural, upward trend in demand.
Consolidation
The industry isn’t just changing — it’s concentrating at breakneck speed. A handful of giants now dominate national egg supplies, wielding serious pricing power. In the U.S., the number of producers has plummeted with 59 farms cranking out 87% of all eggs. Cal-Maine alone controls 16–20% of the market and more than 40 million hens. The pattern repeats across markets: the UK’s Noble Foods sits near 30% share, while in Europe three Ukrainian powerhouses — Avangardco, MHP and Ovostar — rank among the continent’s biggest players. France, Germany and especially Spain are now in the middle of their own consolidation blitz.
Margin Improvements
Historically, egg producers operated on thin margins and faced frequent volatility. Over the past 24–36 months, however, these dynamics have shifted. Elevated prices have improved margins, while the premiumisation trend has created a fast-growing, high-margin segment. Consumers are increasingly willing to pay more for eggs aligned with their values — organic, cage-free, welfare-oriented — creating a dual-market structure: a low-margin commodity segment and a premium segment attracting private equity investors.
At the same time, regulatory pressures — particularly the transition toward cage-free production — require substantial, non-discretionary capital expenditure. As profitability improves and capacity becomes strategically scarce, financial investors are stepping into the sector.
Private equity (PE) interest
One example is the private equity arm of Brazilian investment bank BTG Pactual, which acquired an ~11% stake in Global Eggs by contributing around $300M to help finance the acquisition of Hillandale Farms. Another is U.S. specialist Butterfly Equity, which has been actively expanding differentiated egg platforms. Its portfolio company, Pete & Gerry’s Organic Eggs, has pursued a buy-and-build strategy through acquisitions such as Farmers Hen House, targeting premium and welfare-oriented categories. Broader agribusiness funds such as Paine Schwartz Partners and Proterra Partners, both active across sustainable and animal-welfare-aligned food production, are also watching egg-sector developments closely.
M&A dynamics
The arrival of global multinationals — backed by increasingly active private equity funds — has turned the egg sector into one of the hottest M&A arenas in agrifood. And the logic behind the consolidation wave is hard to ignore:
- Biosecurity is now strategy. Avian influenza has made single-country supply models look dangerously fragile. Retailers and QSR chains want suppliers who can stay online even when one region is hit. Cross-border acquisitions give producers the epidemiological diversification they need.
- Scale wins the price war. Bigger players negotiate better, hold more sway with retailers and secure more stable contract terms.
- Integration is the new moat. Feed costs dictate profitability. Consolidators like Global Eggs, MHP, Cal-Maine, Ovostar and Eurovo are buying feed mills, logistics, packing and processing — and acquiring integrated platforms abroad is often faster and cheaper than building them.
- Demand keeps rising. Eggs remain the most affordable high-quality protein, and per-capita consumption is climbing fast across Asia, the Middle East and Latin America. Local production is essential to compete.
- Regulation pushes the small players out. Stricter welfare, safety and emissions rules — especially in the EU and U.S. — require capex that many smaller farms simply find hard to absorb.
Put together, these forces have created a fleeting but powerful moment: rising profits, soaring demand, tightening regulation and growing financial firepower. The industry’s biggest players are now racing to secure capacity, geography and resilience before the window closes.
Major Transactions
Global Eggs, controlled by Brazilian serial entrepreneur Ricardo Faria, is currently the most active pure-play consolidator. In just two years, it has transformed from a Brazil-centric platform — where it acquired 11 domestic egg-production companies via Granja Faria — into a multinational operator. After purchasing Grupo Hevo in Spain (which itself acquired four additional farms), Global Eggs executed a sector-defining transaction: the $1.1bn acquisition of Hillandale Farms in the U.S., one of the country’s largest egg suppliers.
Cal-Maine Foods — the largest U.S. egg producer — closed six acquisitions in 2023, two more in 2024, and in June 2025 announced its purchase of Echo Lake Foods, further expanding its value-added egg portfolio.
Noble Foods in the UK has also been active, acquiring Just Egg and Hi-Peak Feeds in the last two years to strengthen both its supply chain and its value-added offering.
Eurovo, Italy's leading egg producer, has executed a silent but strategic expansion across Europe, seeking diversification and control over the supply chain. Key acquisitions such as the Italian Waffelman (finished consumer product, where the egg is an essential ingredient), Belgium's Hulstaert (egg products such as processed egg, liquid egg, pasteurized egg, etc.), the UK's Two Chicks (niche liquid egg whites) and, more recently, Spain's Granja Pinilla (geographical positioning and control over the supply chain in Southern Europe), not only extend its geographical footprint but also allow it to enter the lucrative market for value-added products.
MHP, Ukraine’s largest poultry producer, is not a pure egg consolidator but plays a major role in the broader protein chain. In 2024–25, it acquired over 92% of Spain’s Grupo UVESA, a vertically integrated poultry and pork operator. Although UVESA is not an egg producer, the acquisition strengthens MHP’s control across hatcheries, processing and distribution, indirectly shaping egg-supply dynamics and retailer bargaining power.
Valuation Trends and multiples
Rising interest and profitability have pushed valuations upwards. Recent transactions indicate:
- Broader egg farms: 0.6x EV/revenue
- Top-tier “trophy” assets: up to 1.3x EV/revenue (e.g., Hillandale Farms at a $1.1bn valuation)
- Cal-Maine’s acquisition of Echo Lake Foods: ~1.1x revenue (€258M EV)
- Public comparables (as of December 12th 2025):
- Cal-Maine trading at ~1.0x sales (market cap $4.2bn)
- MHP trading at ~0.7x sales (market cap €680M)
These multiples mark some of the highest valuations ever seen in the sector.
Should Mid-Size Producers Sell Into This Consolidation Wave?
A rare exit window has opened for family-owned egg farms. High egg prices are inflating revenue bases, and premium assets (scale above €50M, spare capacity, vertical integration, and high cage-free or ecological content) can command valuations near the top of historical ranges.
Remaining independent, however, increasingly requires substantial investment:
- animal-welfare transitions (e.g., full cage-free compliance),
- biosecurity upgrades,
- logistics redesign and isolation barns,
- digital traceability and ESG reporting,
- and the ability to absorb higher land, labour, energy and feed costs.
The burden falls disproportionately on smaller or less integrated producers, who face rising vulnerability to the sector’s mounting price volatility.
Even so, well-run €50M+ producers with deep integration, cage-free capacity, strong local roots and solid succession plans can continue to deliver standout returns independently. In Europe, the value of local proximity still carries real competitive weight.
Thinking of Selling your Egg Farm?
CDI Global stands uniquely positioned to support you. With international teams of seasoned professionals across key markets — and extensive experience in agriculture and, specifically, the egg sector — we understand the strategic priorities of global consolidators such as Global Eggs or Eurovo. With a strong track record advising egg producers on sell-side transactions, we are uniquely equipped to help owners unlock maximum value in today’s extraordinary market conditions.
By: Carmelo de las Morenas
Author:
Managing Director
Published:
12th January 2026
Format:
Subject:
Industry:
Share:


